
Should You Buy Now or Keep Renting?
Updated: Jul 25
People often get pushed into a bad comparison here. Renting is framed as throwing money away, and buying is framed as the obvious next step. In real files, the decision is more specific. A buyer may be mortgage-eligible and still be better off waiting if the move horizon is short, the cash cushion is too thin, or the likely payment would strain the monthly budget.
Start with timeline, not slogans
If there is a strong chance you will move again in a year or two, buying can become expensive quickly. Closing costs, prepaid items, the down payment, and the cost of selling later all matter. A borrower who buys and then has to move shortly after closing may not stay in the property long enough for the purchase to make financial sense.
If the plan is to stay put for several years, the comparison changes. A fixed mortgage payment may offer more stability than rent increases, and principal reduction may begin building equity over time. The decision gets stronger when the borrower also has enough cash left after closing instead of using every available dollar just to get into the house.
The monthly payment comparison needs to be honest
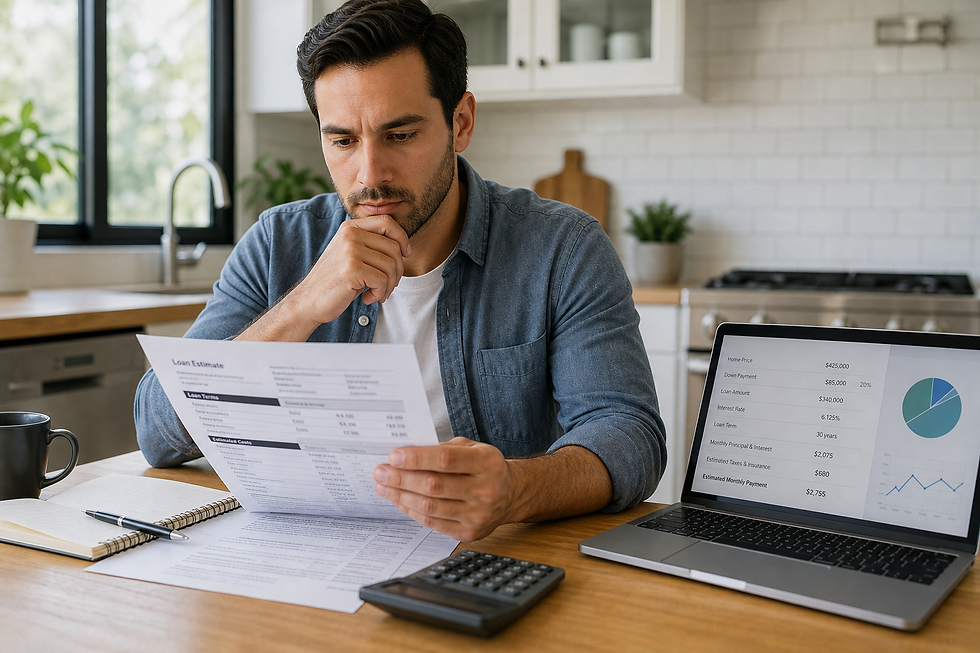
Rent is one number. Buying is several numbers combined. The real housing payment usually includes principal, interest, property taxes, homeowners insurance, mortgage insurance when required, and association dues if the property has them. A buyer who compares rent only to principal and interest is understating the real monthly obligation.
This is where some borrowers misread the decision. They see a mortgage calculator show a payment close to their rent, but once taxes, insurance, and mortgage insurance are added, the monthly housing cost can be several hundred dollars higher than expected.
Scenario
A renter currently pays $1,850 a month and is considering a $240,000 home. With 5% down, the loan amount would be about $228,000 before any financed costs. Assume the monthly principal and interest is about $1,500. Now add $325 for property taxes, $110 for homeowners insurance, and $95 for mortgage insurance. The full monthly housing payment is about $2,030.
That means buying is not roughly equal to the current rent. It is about $180 more per month before maintenance, repairs, or any association dues. If the same borrower expects rent to stay near $1,850 for another year and may need to relocate in 18 months, renting may be the cleaner decision. If that borrower expects to stay five years and can handle the higher payment comfortably, buying may make more sense.
Cash after closing matters as much as cash to close
A buyer who can technically close but would be left with almost no reserves is taking a different risk than a buyer who closes and still has a real cushion. Homeownership comes with repair exposure and less flexibility than renting. Even when the payment works, draining savings to get into the property can make a manageable purchase feel tight within a few months.
That is why the decision is not just whether you can produce the down payment. It is whether you can close, keep enough money in reserve, and still handle the monthly payment without putting the rest of your finances under strain.
Mobility has value too
Renting keeps options open. If a job, school plan, relationship, family need, or preferred neighborhood may change soon, flexibility has real value. Buying works better when the borrower wants payment stability, expects to stay long enough to justify the upfront cost, and has a clear picture of what the full ownership cost looks like.
This is why the same borrower can receive two different recommendations at two different times. The income may already support a mortgage, but a short move horizon or thin post-closing liquidity can still make waiting the better call for now.
What the review should answer
A useful mortgage conversation should not end with you qualify or keep renting. It should answer three specific questions: what payment range currently fits the file, how much cash would be needed to close and still stay comfortable afterward, and whether the borrower's expected timeline makes those numbers practical enough to act on now.
Key Takeaways
Buying is stronger when the timeline is long enough to justify the upfront cost.
The real comparison is current rent versus the full housing payment, not just principal and interest.
A buyer who closes with no cushion is taking a different risk than a buyer who still has reserves afterward.
The right answer is usually a numbers question, not a slogan. DRG Mortgage can compare your likely payment, cash needed at closing, and move timeline so you can tell whether buying now is practical or whether renting a little longer puts you in a better position. If you want to review your numbers, start a pre-approval conversation with DRG Mortgage.
Continue reading: How to Get Pre-Approved Before You House Hunt
Comments