
How to Get Pre-Approved Before You House Hunt
Updated: Jul 25
A strong pre-approval is not just a letter. It is an early file review that tests whether the income, debts, assets, and property plan support the price range you want to shop in.
That matters because many buyers start with an online estimate or a rough verbal number, then find out later that the real monthly payment, counted debts, or required cash changes the range. When that happens after a house is picked, the process gets more stressful and the options get narrower.

What a Useful Pre-Approval Should Answer
Before you schedule showings, a real pre-approval should answer three things clearly:
What monthly payment range fits your numbers right now.
What price range that payment supports once taxes, insurance, and mortgage insurance are included.
What documentation or file issues still need to be cleaned up before an offer is made.
If those answers are vague, the pre-approval is not doing enough work yet.
What the Lender Is Actually Reviewing
A workable review usually goes beyond a credit pull. It should look at your gross qualifying income, monthly debts, available funds, employment structure, occupancy plan, expected cash to close, whether you have a valid state ID, and whether you already know about major credit problems.
For example, if a buyer qualifies better with base salary than with bonus income, that should be identified early. If the buyer has enough for down payment but not enough for closing costs and reserves, that should be identified early too. Those are not small details. They directly change the price range and the loan structure.
The early credit conversation matters for another reason too. If a borrower already knows their score is far below mortgage range, or already knows there are unresolved judgments, collections, charge-offs, or similar problems, that is useful before anyone pays to run credit. A buyer who says their score is around 499 is usually not at the pre-approval stage yet. In that situation, the better next step is usually to talk through readiness issues first instead of pulling credit immediately.
Scenario
A buyer earns $8,200 per month in gross base income and has a $525 car payment, a $75 minimum credit-card payment, and a $210 student loan payment. That is $810 in monthly debt before housing.
Using a 50% DTI example, the file supports up to $4,100 in total monthly obligations. After subtracting the existing $810 in debt, the maximum room for housing is about $3,290.
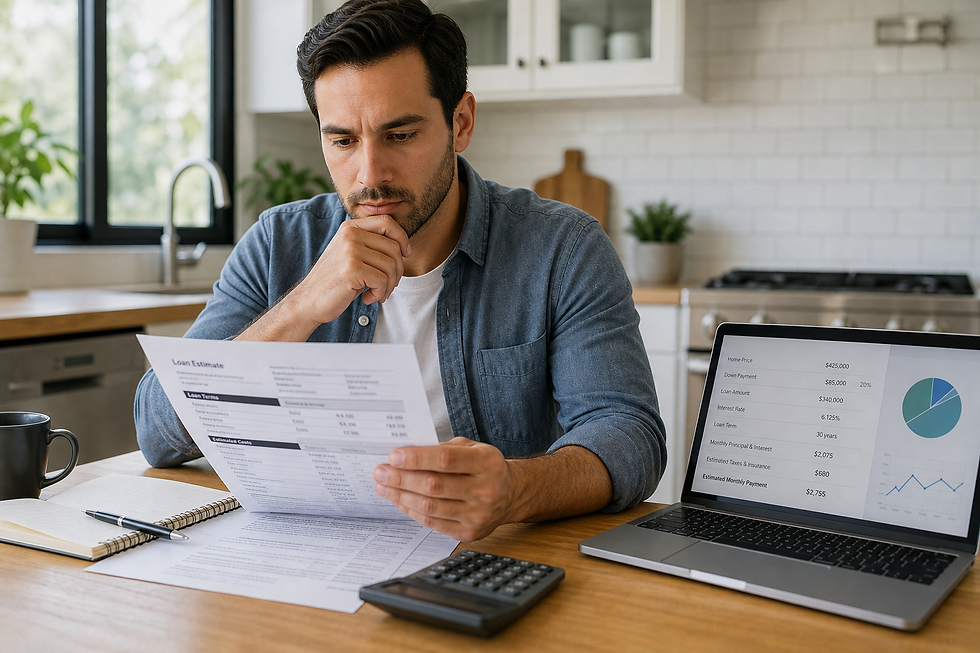
If the buyer is looking at homes around $345,000 with 5% down, the principal and interest payment might land near $2,190. Add $395 for property taxes, $130 for homeowners insurance, and $165 for monthly mortgage insurance, and the total housing payment is about $2,880.
That puts total monthly obligations at about $3,690, or roughly 45.0% DTI. On those numbers, the range may work.
But if the same buyer was assuming they could spend $385,000, the total housing payment could move closer to $3,200. Add the same $810 in other debt and the file reaches about $4,010, which is roughly 48.9% DTI. That is much tighter, and any higher taxes, HOA dues, or payment change could push the file out of range.
That is why a real pre-approval matters before shopping. It can show the difference between a comfortable target range and a number that only works if every detail comes in perfectly.
What Commonly Slows the File Down
Most pre-approval delays are not caused by unusual underwriting problems. They are caused by missing or unclear documentation.
Bank statements are missing pages or show large deposits that have not been explained.
Paystubs are outdated or do not match the income being used.
Bonus, commission, overtime, or self-employment income is assumed to count without enough history to support it.
Cash available is overstated because the buyer is counting funds that are not actually liquid or already have another intended use.
Each of those issues can slow the file because they force the review to pause until the number or source is verified.
What To Have Ready Before the Conversation
A buyer does not need every document in perfect order before the first call, but the conversation goes much faster when these items are close at hand:
a valid state ID,
recent paystubs and the last two years of W-2s or tax returns, depending on income type,
recent bank statements for the funds expected to be used,
a rough estimate of monthly debts beyond what may already show on the credit report,
the approximate price range they want to shop in,
the borrower's approximate credit-score range if they already know it,
and any known issues such as collections, judgments, late payments, gift funds, or co-borrower questions.
When To Start
If you expect to buy within the next 60 to 90 days, this is usually the right time to start. That gives you time to correct a document issue, adjust the price target, compare loan options, or wait for funds to season if the file needs it.
Starting early does not lock you into buying immediately. It gives you a cleaner range and fewer surprises once the right property shows up.
Key Takeaways
A real pre-approval should test payment, price range, and file quality, not just generate a letter.
Taxes, insurance, mortgage insurance, and existing monthly debt can materially change the usable price range.
Most delays come from unclear income or asset documentation, not from unusual underwriting drama.
Starting before house hunting gives you time to fix problems while your options are still wide open.
If you want to know what range actually fits and what still needs to be cleaned up first, a pre-approval review can sort that out before a property is in play.
Continue reading: How Financing Strategy Can Make Your Offer More Competitive
Related checklist: Document Checklist for a Two-Borrower Pre-Approval
Comments