
FHA vs. Conventional: Which Loan Fits the Borrower Better?
Updated: Jul 25
Borrowers often ask whether FHA or conventional is better. The more useful answer is that each option solves different problems. Conventional often brings better rates and can be available with as little as 3% down for some first-time buyers. FHA usually starts at 3.5% down, but it can be more workable when the file needs more credit flexibility or when the borrower needs a larger seller-concession allowance.
This is where borrowers get tripped up. Conventional may be the cleaner long-term structure, but FHA may still be the more practical path if the borrower needs help with approval strength or cash to close. The better answer depends on how the credit, assets, seller concessions, and payment tradeoffs actually land in the file.
What Should Actually Be Compared
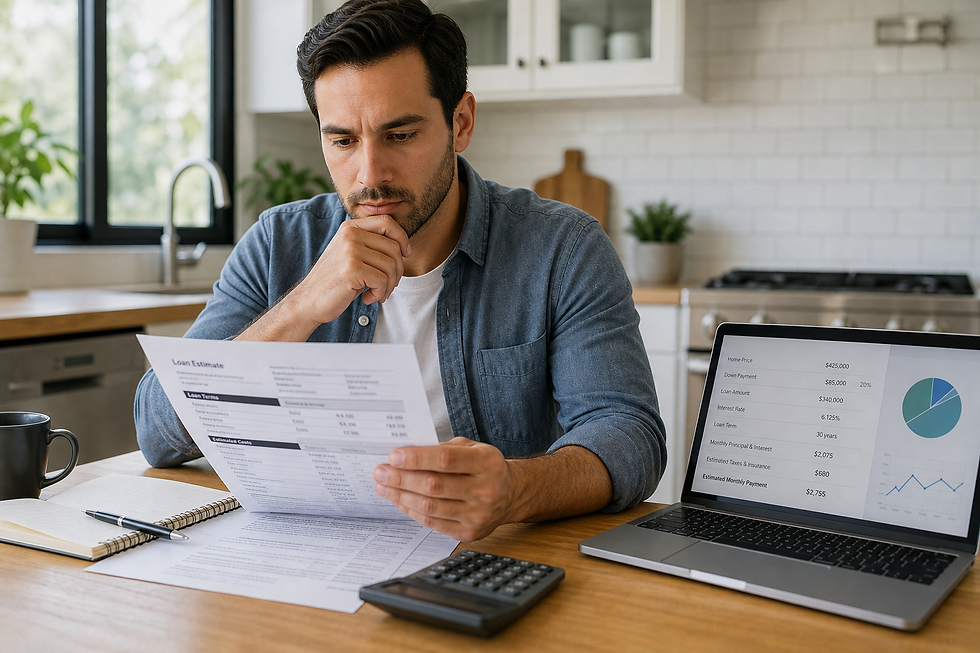
A real FHA-versus-conventional review should compare:
the full monthly payment,
cash required at closing,
upfront and monthly mortgage insurance,
how sensitive the file is to credit score and underwriting strength,
how much seller help is allowed,
and whether the borrower expects to keep the loan long enough for the structure to make sense.
Without that side-by-side comparison, the loan choice usually gets reduced to shorthand that misses the actual tradeoff.
Scenario 1
Assume a first-time buyer is purchasing a $285,000 home, has good credit, expects to stay in the home at least 6 years, and has enough cash to choose between 3% down conventional and 3.5% down FHA.
FHA path: down payment about $9,975, base loan amount about $275,025, upfront mortgage insurance is added to the loan, principal and interest about $1,845, taxes and insurance about $385, monthly mortgage insurance about $190, total monthly payment about $2,420.
Conventional path: down payment about $8,550, loan amount about $276,450, no upfront FHA-style mortgage insurance, principal and interest about $1,805, taxes and insurance about $385, monthly mortgage insurance about $92, total monthly payment about $2,282.
In this example, conventional does not require more down payment. It actually requires about $1,425 less down than FHA, while still producing a monthly payment about $138 lower.
Over the first 36 months, that monthly difference adds up to almost $5,000 in payment savings. That means the borrower starts with less cash out of pocket and still gets the lower monthly payment. In a file like this, conventional is often the stronger offer because the rate is usually better, the monthly mortgage insurance is lighter, and the overall risk profile is often easier to process.
This is the kind of borrower who often should not default to FHA just because FHA is familiar. If the credit is solid and the file is clean, conventional can be cheaper both upfront and over time.
Scenario 2
Now assume a different borrower is buying the same $285,000 home but has weaker credit and only about $14,500 in liquid assets available. The borrower has good income and a manageable DTI, but does not have enough cash to absorb a larger gap at closing without seller help.
Conventional path: 3% down is about $8,550. If closing costs land at $11,000, total cash need is about $19,550 before credits. With only $14,500 available, the borrower is short about $5,050. A 3% seller-concession cap is about $8,550, but weaker credit may still make the file less forgiving overall.
FHA path: 3.5% down is about $9,975. If closing costs land at $11,000, total cash need is about $20,975 before credits. With only $14,500 available, the borrower is short about $6,475. FHA may allow up to 6% seller concessions, or about $17,100 on this price. FHA can sometimes work with scores as low as 500 when there are strong compensating factors.
In this kind of file, FHA may be more advantageous even if the rate or monthly payment is not as attractive as conventional. The reason is not that FHA is automatically cheaper. The reason is that the borrower may need both the credit flexibility and the higher concession ceiling to close the asset gap without bringing in outside funds they do not have.
FHA can come with more documentation and more friction, especially when the file is weaker. If the borrower does not fit a straightforward approval path, FHA may take more explanation and support than a clean conventional file. But when the issue is weaker credit or not enough liquid assets for both down payment and the usual $9,000 to $13,000 closing-cost range, that extra work can still be the right tradeoff.
Why FHA Sometimes Wins
FHA often becomes attractive when a borrower needs more flexibility around credit profile, higher ratios, or available cash. A borrower may not choose FHA because it is cheaper. The borrower may choose it because it gives the file a more realistic path to approval or because the higher seller-concession limit helps solve the cash-to-close problem.
Why Conventional Sometimes Wins
Conventional often becomes stronger when the borrower has cleaner credit and enough overall file strength to qualify without needing FHA's flexibility. In those files, the better rate, lighter mortgage insurance, and lower-risk profile can make conventional both cheaper and easier to process.
That is especially important for a borrower who expects to stay put for several years. The monthly savings can build quickly, and the long-term mortgage-insurance behavior is often more favorable.
Why the Loan Type Can Affect Offer Strength
The loan type can also matter before closing costs or long-term savings are even discussed. In competitive purchase situations, a conventional pre-approval is often seen as the stronger offer profile.
That is partly because conventional financing usually suggests a cleaner buyer profile and partly because it is often viewed as the easier, faster file to originate. An FHA pre-approval can sometimes be seen as less competitive because listing agents and sellers may assume the borrower has weaker credit, tighter cash, or a file that could take more work to get through underwriting.
That perception is not always fair, and it is not always correct. But it is real enough that it should be part of the comparison when a borrower expects to compete for a home.
What Borrowers Usually Miss
Many borrowers compare only down payment or only rate. That misses the real question.
Conventional may actually require less down than FHA for some first-time buyers because 3% down is possible on some files.
FHA may still be the better answer when seller concessions or credit flexibility matter more than monthly payment.
The better loan can flip depending on whether the borrower is solving for approval strength, monthly cost, or liquidity after closing.
Key Takeaways
Conventional often brings better rates and, for some first-time buyers, can require only 3% down instead of FHA's 3.5%.
FHA can be more advantageous when the file needs weaker-credit flexibility or up to 6% seller concessions to solve the cash problem.
The comparison should include payment, cash to close, mortgage insurance, concessions, credit profile, and time horizon.
Conventional is often the lower-risk, easier-to-process file, while FHA can require more documentation and may be perceived as a less competitive offer in a bidding situation.
The cleanest way to choose between FHA and conventional is to compare both paths on the same property with the same real numbers, then decide which tradeoff actually fits the borrower's plan.
Continue reading: Using Gift Funds the Right Way in a Purchase Transaction
Comments